
Research: Trade
Maritime chokepoints
Stephan Maurer, Luke Heath Milsom and Ferdinand Rauch
World trade remains dangerously dependent on a handful of shipping lanes
Despite the digitisation of the global economy, world trade is still only as resilient as the physical routes it depends on. Around 90% of freight still travels by sea and the shipping network does not always run smoothly (Kaluza et al, 2010). Traffic between regions is often forced through a small number of "chokepoints", including straits and canals. When these are disrupted, the consequences can be significant.
After the container ship Ever Given ran aground and blocked the Suez Canal for six days in March 2021, the World Trade Organisation estimated that the stoppage knocked somewhere between $6bn and $10bn off global trade volumes. The disruption made headlines, rattling stock markets and inspiring countless memes.
Many of the arteries that carry the bulk of world trade are vulnerable in other ways. Attacks by Houthi rebels on shipping in the Red Sea regularly disrupt that route. Drought has led to reduced water levels and restrictions on the size of ships that can pass through the Panama Canal. And the closure of the Strait of Hormuz during the current war between Iran and the United States has contributed to both an energy crisis and increased inflation in much of the world (Hosein and Saridakis, 2026).
In a new study, we compare quantitatively, for the first time, just how exposed world trade is to several key waterways.
Modelling a world without its shortcuts
We measure sea routes between 455 ports with a statistical model of trade that lets us simulate what would happen if a major route closed or if a new one opened.
We simulate shutting three shipping lanes: the Panama Canal (which connects the Caribbean Sea with the Pacific Ocean), the Suez Canal (between the Red Sea and the Mediterranean Sea) and the Strait of Malacca (between the Indian Ocean and the South China Sea).
We also look at opening two new routes: a year-round Northwest Passage (connecting the Atlantic and Pacific oceans through the Arctic north of Canada) and a proposed canal across Thailand’s Kra Isthmus (see box). The latter scheme would lower the distance for many shipment routes between China or Japan and Europe, although the Thai government has also considered a land-bridge project instead of a canal.
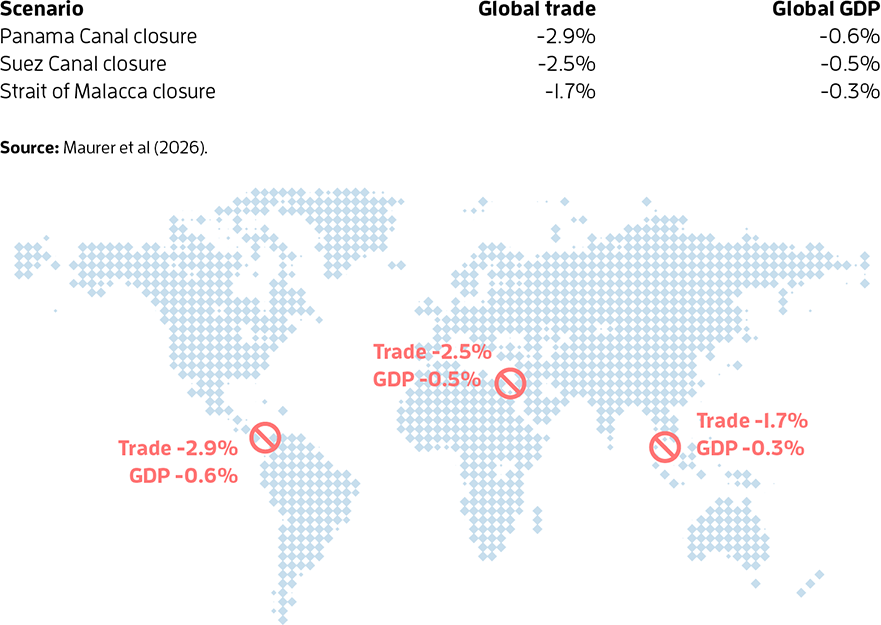
Our numbers show a similar disruption potential for all three major waterways that we examine. A permanent closure of Panama would cut global trade by about 2.9%; closing Suez would cost the world 2.5%; and closing Malacca would cost 1.7% (Table 1).
Each is important enough, on its own, to inflict damage to global trade of roughly the same order of magnitude. But substitutability is also relevant. If Suez closed, ships could still reach Asia from Europe by sailing around the South Africa's Cape of Good Hope. This route is longer and costlier, but also well established.
Losing Panama is somewhat more damaging in relative terms: it severs the link between the Atlantic and Pacific coasts of the United States, requiring a very lengthy detour around the southern tip of South America.
Countries that border key routes are hit hardest by disruptions: if the Suez Canal closed, Egypt would lose roughly 8% of its GDP
Table 1: Simulated global effects of closing the three major maritime chokepoints
From trade to living standards
Lost trade is not an abstract number. It also leads to lower overall GDP. Our model translates the Panama scenario into an immediate 0.6% hit to world GDP, with Suez costing 0.5% and Malacca 0.3%. These figures capture the moment just after a closure, before firms and shippers have had time to adjust. Over the longer term, the losses are likely to reduce as the system will find workarounds.
The global averages disguise substantial variation across countries. For the United States, the Panama Canal is critical for connecting its east and west coasts: a closure would cut US trade by more than 10%. China, by contrast, would barely notice, with a marginal trade drop of 0.1%.
Perhaps unsurprisingly, China's vulnerability lies in the Strait of Malacca. This is the chokepoint through which much of its energy imports and manufactured exports must pass. Our model has Chinese trade falling by 2.3% if that closed. For Europe, Suez is the binding constraint. A closure would cut Greek trade by more than 8% and Romanian trade by over 7%, with Italy losing around 5%.
The costs of maritime disruptions come less from the direct loss of trade than from damage to production chains
But it is the countries that border these routes that are hit hardest of all. If Suez closed, Egypt would lose over 40% of its trade and roughly 8% of its entire GDP. When we use a model-driven measure of national wellbeing, which is broader than mere GDP and trade flows, Mexico and Panama each lose around 4% in the Panama scenario, Qatar loses almost 3% in the Suez scenario, and Malaysia loses nearly 4% if Malacca closes.
Does the model match reality?
Trade statistics are published with a lag, which makes it hard to test a model like ours against real world events as they happen. But financial markets react in real time. We compare our model's predictions with how stock markets in 15 countries actually moved while the Ever Given blocked Suez.
We find that countries more exposed to the Suez route according to our model did tend to see sharper market falls during the blockage. But with only 15 countries in the comparison, and India exerting an outsized pull on the result, we would flag this as suggestive rather than conclusive evidence.
Our headline estimates do not reflect the full impact of closures. When we extend the model to account for the way in which disruptions ripple through global supply chains - drawing on a methodology developed for solving gravity models (Campos et al, 2025) - the estimated losses from a chokepoint closure are 50% higher than in our simple baseline. That's because much of the true cost of these disruptions comes not from the direct loss of trade itself, but from the subsequent damage to production chains upstream. This finding is particularly important for those industries that have built their supply chains around the assumption that goods will always get through.
New shipping routes could matter far more as insurance against future disruptions than as growth engines in their own right
New routes are a slow burn, not a quick win
If closures are costly, do new waterways boost trade? According to our results, the answer is not by much, at least not immediately. Opening a Kra Canal would raise global trade by only 0.7%; a fully navigable Northwest Passage would add just 0.6%.
The modest figures reflect how deeply path-dependent shipping networks are. Ports, fleets and supply chains have spent decades organising themselves around the routes that already exist, so a new shortcut starts out serving only a narrow slice of traffic.
But while a closure does its damage immediately and the cost fades over time as the system adapts, opening works the other way round - gains are small on day one and grow over decades, as industrial clusters and trading relationships gradually adjust and new trade infrastructure sets up along the route. So new routes could end up mattering far more as insurance against future disruption elsewhere than as growth engines in their own right.
What this means for policy
Our study finds not that one canal is more important than another, but that world trade remains highly dependent on a small number of locations. That matters for policy in four ways.
First, having a number attached to the risk lets governments and firms weigh the cost of securing a route against the cost of leaving it exposed. It quantifies for China and the United States why Malacca and Panama are so critical for their economic security.
Second, new routes through the Arctic or a Kra Canal are unlikely to transform global trade flows quickly, but they could offer welcome insurance against problems elsewhere.
Third, because the sharpest losses come in the immediate aftermath of a shock, before adjustment mechanisms can kick in, building resilience through diversified suppliers and flexible logistics matters more than waiting for alternative routes to appear as substitutions.
And finally, since a substantial share of the ultimate cost is transmitted through supply chains rather than trade volumes directly, resilience planning should look beyond the route itself to the production chains that depend on it.
The Kra Plan: a short cut across Thailand
The Kra Plan, a canal cutting through the Kra Isthmus in Thailand, has endured many iterations - and obstacles - since its conception. The idea dates back to 1677 but was abandoned due to the technological limitations of the era. Renewed French interest in the project during the 19th century was curtailed by a wary Siamese government, seeking to preserve good relations with Britain.
Contemporary ambitions for a 100-kilometre waterway connecting the Gulf of Thailand with the Andaman Sea saw Thai and Japanese investors conducting a feasibility study in the 1980s before political tensions in the region undermined the project.
If constructed, the Kra Canal would be an alternative to the Strait of Malacca - shortening transit routes around Singapore and Malaysia by 1,200 to 1,400 nautical miles, and sailing time by up to four days. The route, linking the Indian and Pacific Oceans, would also ease the "Malacca dilemma" of China, which is critically dependent on the chokepoint for its oil imports and manufacturing trade. The US has defence-cooperation partnerships with Indonesia, Malaysia, Singapore and Thailand, enabling it to have oversight of critical shipping lanes for Beijing's energy supply chains. While Beijing has not openly endorsed any plans, an alternative shipping route would lessen the geoeconomic risk of the Strait of Malacca for China, as well as provide another door to the Indian Ocean.
For Thailand, even as the Kra Plan offers immense economic trading power, it would geographically split the nation in two, potentially reinforcing tensions with separatist movements in the south. Further, low-end costs for the project are estimated at around $18bn, posing a financial hurdle for the Thai government along with concerns over an influx of foreign investment necessary for the project. As an alternative, the government recently considered a "land-bridge" as a way to connect upgraded deep-water ports in the Ranong and Chumphon provinces - but plans have been put on hold due to the high economic costs and environmental risks associated with construction.
By Lia Bergin
This article summarises Maurer, S., Milson, L. and Rauch, F. (2026) The fragility of the global trading system. CEP Discussion Paper No. 2186. An earlier version first appeared on LSE Business Review.
Stephan Maurer is a Ramón y Cajal Researcher at the UPF Barcelona School of Management and a research associate in CEP's labour programme. Luke Heath Milsom is an assistant professor of economics at KU Leuven and an associate at the Institute for Fiscal Studies. Ferdinand Rauch is a professor of economics at the University of St Gallen in Switzerland and a research associate in CEP's urban programme.
Further reading
Campos, R., Reggio, I. and Timini, J. (2025) 'ge_gravity2: A command for solving universal gravity models', The Stata Journal, 25(4).
Hosein, R. and Saridakis, G. (2026) 'In what ways does the Middle East conflict affect global trade and growth?', LSE Business Review.
Kaluza, P., Kölzsch, A., Gastner, M.T. and Blasius, B. (2010) 'The complex network of global cargo ship movements', Journal of the Royal Society Interface, 7(48), pp. 1093-1103.
20 October 2026 Paper Number CEPCP745
Download PDF - Maritime chokepoints
This CentrePiece article is published under the centre's Trade programme.
This publication comes under the following theme: Trade Policy and barriers to international economic integration